Frequently Asked Bankruptcy Questions
 Chapter 13 and Chapter 7 bankruptcy questions answered here. This page contains a lot of detailed bankruptcy option information. Please read all of the information and give us a call for your free consultation so that we can help you put a game plan together to help solve your financial situation. Over the past 34 years, our office has helped hundreds of Washington client file for Chapter 7 and Chapter 13 protection in order to get their lives organized and Get a Fresh Start!
Read our client reviews to see why we are your Best Choice!
We help people stop garnishments and save their houses all over the Puget Sound area. Federal Way, Tacoma, Puyallup, Fife, Lake Tapps, Auburn, Black Diamond, Kent, Des Moines, Sea-Tac, and Seattle.
Attorney Consult and Case Preparation by Zoom
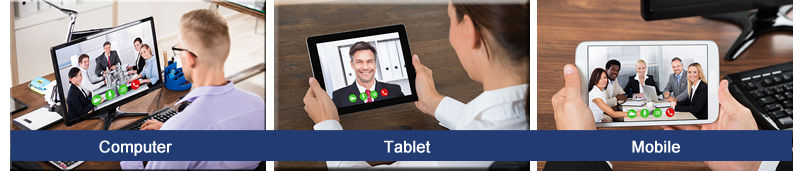
It’s easy to meet with me.
Now you can be anywhere and get the best lawyer for your case. *For Washington, we handle Estate Planning, Probate and Bankruptcy cases. For Oregon, Idaho and Arizona we only handle Estate Planning matters.*
You will be able to video live stream the conference with your smart phone, Ipad or desktop computer. Fast and easy for you.
We send you a link that you click to join the conference. No special hardware required. During the meeting I will answer your Chapter 13 and Chapter 7 bankruptcy questions.
Video and voice available on my end. You can choose to also join by video OR you can simply join by voice. It’s your decision.
(253) 815-6940
(24 hours a day – 7 Days a Week) Call Anytime!
Or use our easy form submission.
We are a debt relief agency. We help people file for bankruptcy relief under the Bankruptcy Code
The first step in taking control of your finances is to delegate to the Law Offices of Christopher A. Benson, PLLC as your agent and representative to take your creditor calls, stop creditor harassment, stop creditors from taking your pay, salary, bonuses, cash and bank accounts. You need to use your best judgement to stop a creditor’s judgment and protect your funds. We can counsel you through the process.
Recovery of garnished funds may be possible in some bankruptcy cases, depending on the timing, the amount transferred, applicable exemptions and other legal requirements and defenses. A refund is not automatic or guaranteed. Filing bankruptcy generally pauses covered collection lawsuits through the automatic stay, subject to exceptions and court orders; it does not automatically cancel every current or future lawsuit. Sources: 11 U.S.C. § 547; 11 U.S.C. § 522; 11 U.S.C. § 362. We will help you defend your federally protected financial rights and assets. Save your pay check. Give us a call or fill out the easy email link and set up your free initial consultation to find out what options are available to you.
Source: US Courts
May an employer terminate a debtor’s employment solely because the person was a debtor or failed to pay a discharged debt?
Chapter 13 and Chapter 7 bankruptcy questions answered.
The answer is No.
The law provides express prohibitions against discriminatory treatment of debtors by both governmental units and private employers. A governmental unit or private employer may not discriminate against a person solely because the person was a debtor, was insolvent before or during the case, or has not paid a debt that was discharged in the case. The law prohibits the following forms of governmental discrimination: terminating an employee; discriminating with respect to hiring; or denying, revoking, suspending, or declining to renew a license, franchise, or similar privilege. A private employer may not discriminate with respect to employment if the discrimination is based solely upon the bankruptcy filing.
In order to file bankruptcy, certain requirements must be met. It is important that you provide complete accurate information to our firm and to the Bankruptcy Court. A fundamental goal of the federal bankruptcy laws enacted by Congress is to give debtors a financial “fresh start” from burdensome debts. The Supreme Court made this point about the purpose of the bankruptcy law in a 1934 decision:
It gives to the honest but unfortunate debtor…a new opportunity in life and a clear field for future effort, unhampered by the pressure and discouragement of preexisting debt.
Local Loan Co. v. Hunt, 292 U.S. 234, 244 (1934). This goal is accomplished through the bankruptcy discharge, which releases debtors from personal liability from specific debts and prohibits creditors from ever taking any action against the debtor to collect those debts
1. What is the bankruptcy means test?
The Chapter 7 means test compares income calculated under bankruptcy rules with Washington’s median income for the same household size. Depending on that comparison, an additional calculation of income and allowable expenses may be required.
Washington annual median income figures, effective April 1, 2026 and verified October 20, 2026:
- 1 person: $88,585
- 2 people: $107,100
- 3 people: $131,737
- 4 people: $156,567
- Add $11,100 for each additional household member.
These are not absolute income limits for filing bankruptcy. If your calculated annual income is at or below the applicable median, you generally do not need to complete the additional Chapter 7 means-test calculation. Above-median income does not automatically disqualify you from Chapter 7; allowable expenses and other applicable rules must be considered. Passing the income comparison alone does not guarantee eligibility or a discharge. Sources: 11 U.S.C. § 707(b); U.S. Courts: Chapter 7 bankruptcy.
Chapter 13 uses related income calculations to help determine repayment-plan duration and required payments. Source: U.S. Courts: Chapter 13 bankruptcy. The applicable figures depend on your filing date and can change. Consult the U.S. Trustee’s current data and obtain advice about your circumstances.
2. You must disclose all of your assets, the liquidation value of your assets and any transfers you have previously made.
3. Tax-return requirements depend on the bankruptcy chapter. In Chapter 13, required returns for taxable periods ending during the four years before filing generally must be filed with the appropriate tax authorities by the day before the first scheduled meeting of creditors, subject to the extension provisions in 11 U.S.C. § 1308. In Chapter 7 and Chapter 13, the debtor must also provide the trustee with a copy or transcript of the required federal income tax return for the most recent tax year ending before the case began for which a return was filed, at least seven days before the first date set for the meeting. Review any missing returns and document requirements with your attorney. Sources: 11 U.S.C. § 1308; 11 U.S.C. § 521.
4. Before filing, an individual generally must complete credit counseling from an agency approved by the U.S. Trustee for the district where the case will be filed, subject to limited statutory exceptions. If spouses file a joint petition, each must receive a certificate in that spouse’s name, even if they attend the same session. Tell the agency at the beginning that both spouses need certificates. Fees vary by provider. Approved agencies must disclose their fees and fee-waiver or fee-reduction policies and provide counseling without regard to ability to pay. Check the U.S. Trustee’s current list of approved agencies before selecting a provider. Sources: 11 U.S.C. § 109; 11 U.S.C. § 111; DOJ UST Credit Counseling FAQs; DOJ Credit Counseling and Debtor Education Providers.
Choose a provider approved by the U.S. Trustee for the district where your case will be filed. A provider may be approved for more than one district; check the appropriate current list for credit counseling or debtor education. Sources: DOJ Credit Counseling and Debtor Education Providers; 11 U.S.C. § 111.
Tell the credit agency up front that you need the certificate in order to file bankruptcy and that will expedite the counseling process.
What is the “credit counseling” class? Can It Be Done Online?
Chapter 13 and Chapter 7 bankruptcy questions answered here.
Yes. The Credit Counseling class can be done online, over the telephone or in person. The class provider issues a Certificate of Counseling that must be filed in order to file your Chapter 7 or Chapter 13 case.
The credit counseling course must be completed prior to filing bankruptcy. Upon completion of the credit counseling class (either online or on the phone) which takes between 30 minutes to an hour and your numbered completion certificate will be emailed to you. You must provide the certificate of completion to our firm so that we can file it at the same time as we file your initial bankruptcy filing.
Credit counseling generally must be completed during the 180-day period ending on the bankruptcy filing date, not simply within six calendar months. Limited statutory exceptions apply. If another counseling session is needed, ask the provider about its fees and fee-waiver or fee-reduction policy. Sources: 11 U.S.C. § 109; DOJ UST Credit Counseling FAQs.
5. You must attend the meeting of creditors required in your case. We will represent you at this meeting. Follow the meeting notice and the trustee’s instructions for providing government-issued photo identification and acceptable evidence of your Social Security number, or a written statement that you do not have a Social Security number. A Social Security card is not the only acceptable evidence. Provide identification documents securely as instructed by the trustee. Sources: DOJ Section 341 Meeting of Creditors.
6. You must also complete a Personal Financial Management Instruction Course (Debtor Education Course) pursuant to 11 USC 111 sometime after you file your bankruptcy but complete it before you discharge in bankruptcy can be granted. You cannot complete both the Credit Counseling course and the Debtor Education Course at the same time.
The Certificate of Completion of the Debtor Education Course has to be filed with the Bankruptcy Court before you bankruptcy can be closed. Please refer to the handout we have provided you entitled “Before You File Personal Bankruptcy.”
If husband and wife filed a joint bankruptcy petition, both parties have to obtain a certificate in their own name.
The Debtor Education Class usually takes longer than the pre-bankruptcy credit counseling class and costs between $50 and $100. For debtor education, choose a provider approved by the U.S. Trustee for the district where your case is filed. Sources: DOJ Credit Counseling and Debtor Education Providers; 11 U.S.C. § 111.
The list of approved Debtor Education Course Providers can be found at www.justice.gov – Debtor Education Course Providers
We have printed out and provided you a list. However, once again Approved Agencies are added and deleted on a regular basis; therefore, you are advised to view the most current approved list from the website above.
Choose a provider approved by the U.S. Trustee for the district where your case will be filed. A provider may be approved for more than one district; check the appropriate current list for credit counseling or debtor education. Sources: DOJ Credit Counseling and Debtor Education Providers; 11 U.S.C. § 111.
7. Court Filing Fees:
Our Firm Charges attorney fees for work performed in bankruptcy filings. Attorney fees are addressed in the Law Firm Contract. Court filing fees are separate from our attorney fees and may change. For current filing, conversion, reopening and other court fees, accepted payment methods and applicable exceptions, consult the U.S. Bankruptcy Court for the Western District of Washington’s official Filing Fees page. Sources: WAWB Filing Fees.
What can the debtor do if a creditor attempts to collect a discharged debt after the case is concluded?
Chapter 13 and Chapter 7 bankruptcy questions answered here.
The answer is No.
If a creditor attempts collection efforts on a discharged debt, the debtor can file a motion with the court, reporting the action and asking that the case be reopened to address the matter. The bankruptcy court will often do so to ensure that the discharge is not violated. The discharge constitutes a permanent statutory injunction prohibiting creditors from taking any action, including the filing of a lawsuit, designed to collect a discharged debt. A creditor can be sanctioned by the court for violating the discharge injunction. The normal sanction for violating the discharge injunction is civil contempt, which is often punishable by a fine.
Call the Law Offices of Christopher A. Benson, PLLC to schedule your free consultation.
(253) 815-6940 Call Anytime!
Law Offices of Christopher A. Benson, PLLC
1814 S. 324th Pl. Suite B
Federal Way, WA 98003
Evening and Weekend Appointments Available. Our website contains additional information to answer your Chapter 13 and Chapter 7 bankruptcy questions. Please look around and watch our videos.
Bankruptcy Attorney doing business in Federal Way, Tacoma, Auburn, Kent, Fife, Des Moines, Seattle, Lake Tapps, Puyallup, Bonney Lake + more!
For those clients with financial problems – We are a debt relief agency. We help people file for bankruptcy relief under the Bankruptcy Code.

CALL FOR A FREE CONSULTATION
(253) 815-6940